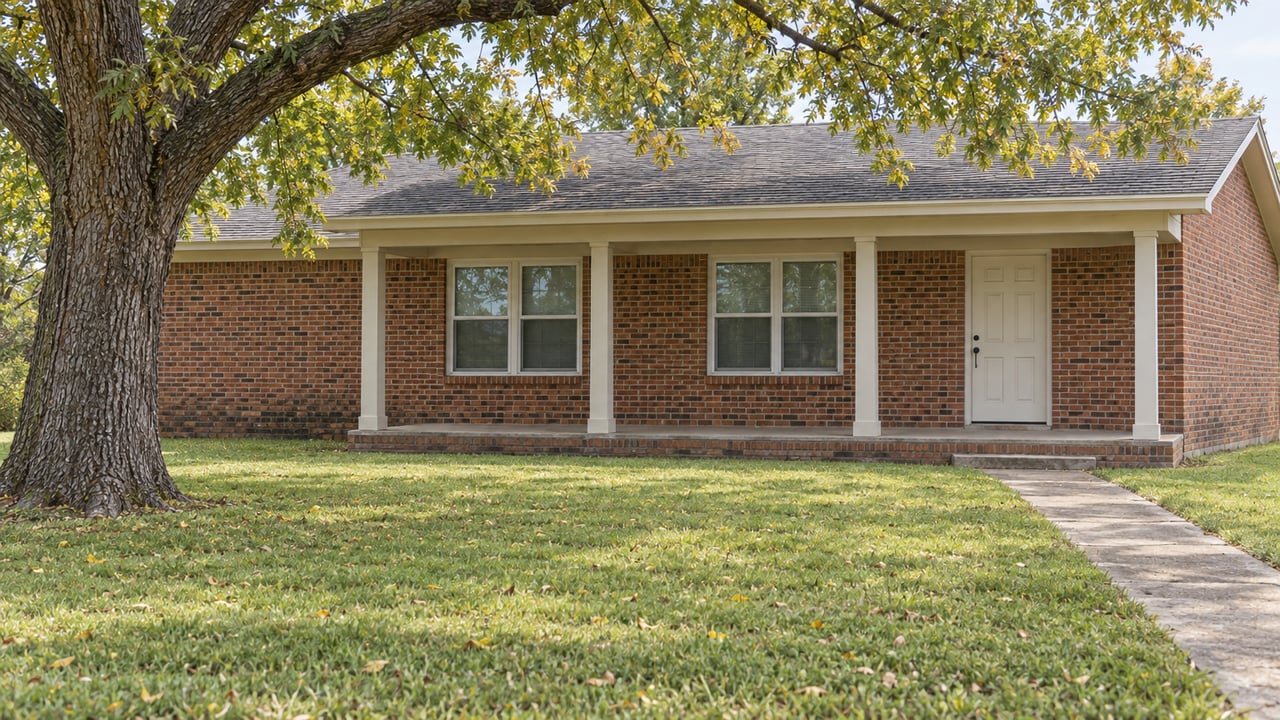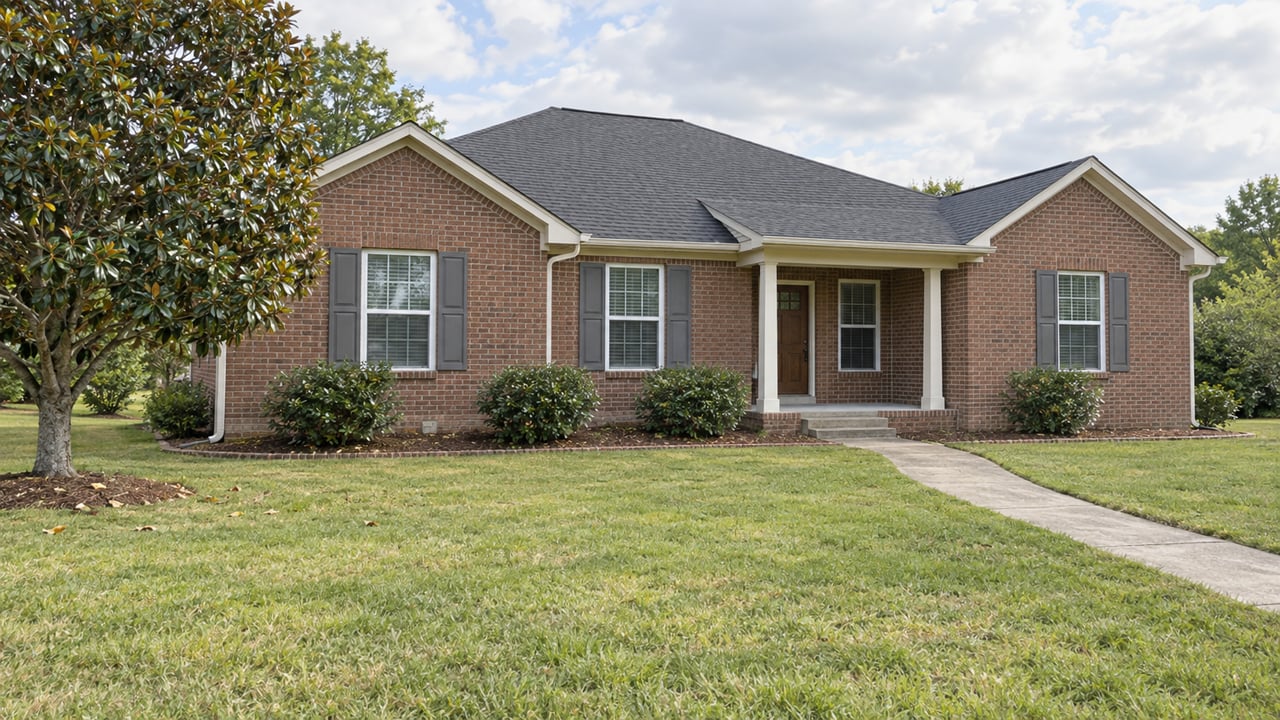
Walk two Grand Bay listings side by side and the math looks simple. One is a five-year-old brick home on an acre, three bedrooms, asking somewhere in the low $200s. The other is a new build in Windmill Palm Estates or Dees Plantation, similar bedroom count, similar acreage, priced $100,000 or more above it. The easy explanation is that new means nicer: quartz over laminate, a smart thermostat instead of a dial, a two-car garage with a 220V outlet already wired for an EV. All true. None of it is the real reason for the gap.
The real reason is sitting in a folder the buyer usually doesn't ask to see: the wind insurance quote.
Two Communities, One Certification
D.R. Horton is building two active communities in Grand Bay right now. Windmill Palm Estates sits at the intersection of Dawes Road and Hi Fields Road, and Dees Plantation is a short distance away, close enough to the family-owned Dees Pecan Company that the builder's own marketing mentions it as a neighbor. Both communities are priced the way new construction usually is: the Kingston floor plan at Windmill Palm Estates lists from $357,900, the Emma plan at Dees Plantation from $310,900.
What Windmill Palm Estates has, and what almost never shows up in the listing description a buyer skims first, is a built-in IBHS FORTIFIED Gold Home certification on every house in the community, confirmed on the builder's own floor plan pages. That's not a marketing badge. It's a specific, third-party-verified construction standard developed by the Insurance Institute for Business and Home Safety, and in Alabama it comes with an insurance discount. Dees Plantation shares the same builder, the same smart home package, and a similar spec sheet, so buyers looking there should ask directly whether the same FORTIFIED certification applies to the specific home under contract rather than assuming it carries over automatically.
| Windmill Palm Estates (Kingston) | Dees Plantation (Emma) | Typical older Grand Bay home | |
|---|---|---|---|
| Starting price | $357,900+ | $310,900 | Varies, often well below new construction on a per-square-foot basis |
| Square footage | 2,246 to 3,127 | 2,246 to 3,127 | Varies |
| FORTIFIED Gold certified | Confirmed, built-in | Same builder, confirm per contract | Only if retrofitted separately |
| Wind insurance discount | FORTIFIED discount | Ask before you write the offer | Not automatic |
What FORTIFIED Actually Buys You
FORTIFIED certification isn't cosmetic. It covers roof deck attachment, sealed roof sheathing, hardened openings, and a handful of other construction details that reduce wind and wind-driven rain damage in a hurricane. Alabama built a real financial incentive around it: homeowners with a FORTIFIED designation get a discount on the wind portion of their insurance premium, and coastal homeowners can see up to 35 percent off that portion, according to Smart Home America's summary of the state's incentive structure. Inland homeowners see smaller but still meaningful reductions, typically up to 20 percent.
They're comparing two different long-term insurance cost structures, and in a Gulf Coast zip code where wind coverage is a real line item, that difference compounds every renewal.
There's also a resale angle worth knowing even if you're buying to stay. A study conducted by the University of Alabama, cited by the state's Strengthen Alabama Homes program, found that FORTIFIED homes sell for nearly 7 percent more than comparable non-FORTIFIED homes. Separately, a University of Alabama-led analysis of more than 40,000 insured Gulf Coast properties, commissioned by the Alabama Department of Insurance, found FORTIFIED homes held up measurably better during Hurricane Sally than conventionally built ones. Buyers aren't paying a premium for a certificate. They're paying for a documented performance difference that shows up both in storm damage and in resale value.
The Retrofit Path Exists, and It's Narrower Than It Sounds
If the new-construction premium feels steep, there is a way for an existing Grand Bay homeowner to get the same certification and the same discount without buying new. The state's Strengthen Alabama Homes program will pay up to $10,000 toward bringing an existing roof up to FORTIFIED standard, and the grant covers the full cost of that work up to the cap. It sounds like a straightforward workaround. The eligibility rules make it considerably narrower in practice.
A few conditions matter most for anyone weighing new construction against an older home with a plan to retrofit later:
- The home has to be an existing, owner-occupied, single-family primary residence. Rentals, condos, townhomes, and mobile homes don't qualify.
- The home cannot be listed for sale at any point during the process. A seller can't use this grant to boost a listing right before putting it on the market, and a buyer can't ask a seller to run it as part of the transaction.
- Funding opens quarterly and closes the moment it's gone. For Mobile County, the next 2026 window opens October 6 at 9:00 a.m., with the program's own guidance warning that being even a few minutes late to apply can mean waiting until the next quarter.
- Evaluator fees, typically $300 to $500, come out of the homeowner's pocket separately from the grant, and any mitigation cost above the $10,000 cap is the homeowner's responsibility too.
That last rule about listings is the one buyers most often miss. It means the discount isn't something you can layer onto a purchase in progress. If you close on an older Grand Bay home this fall, you become eligible to apply for the grant once you own and occupy it as your primary residence, but only at the next open window, and only if you get through the portal before the funding runs out.
What This Actually Means When You're Comparing Two Listings
None of this means new construction is automatically the better financial choice, or that an older Grand Bay home is a bad one. Plenty of buyers value the acreage, the mature trees, or the lower entry price that older homes in Grand Bay still offer, and those trade-offs are real. What it does mean is that the sticker price gap between a Windmill Palm Estates or Dees Plantation home and a similarly sized older home isn't purely a size-and-finish story. Part of that gap is the buyer prepaying, through the purchase price, for a wind insurance discount and a resale premium that an older home would need a separate application, a narrow quarterly window, and several months of waiting to catch up to.
If you're weighing both paths, the practical move is to ask for the actual wind insurance quote on each home before you compare monthly payments, not just the mortgage estimate. A $100,000 price gap can look very different once you know one of those homes is already collecting a 20 to 35 percent discount on part of its premium and the other isn't, at least not yet.
Frequently Asked Questions
Does every new-construction home in Grand Bay come with FORTIFIED certification automatically? Windmill Palm Estates, built by D.R. Horton, is confirmed on the builder's own materials as FORTIFIED Gold Home certified. Dees Plantation is built by the same company with a similar spec sheet, but don't assume the certification carries over without confirming it on the specific home you're under contract for. If you're looking at new construction from any builder, ask directly and get the certification in writing.
Can I apply for the Strengthen Alabama Homes grant as soon as I close on an older home? You become eligible once you own and occupy the home as your primary residence, but you'll need to wait for the next open application window and get your documentation in before the funding is claimed. For Mobile County in 2026, the remaining window opens October 6 at 9:00 a.m.
Does the FORTIFIED discount apply to the whole insurance premium or just part of it? Just the wind portion. In coastal Alabama that's often a substantial share of the total premium, but it's not the entire bill, and your total savings will depend on how your specific policy is structured.
Is the grant a loan I'll have to pay back? No. It's a grant funded through Alabama's insurance industry, not the state budget, and approved homeowners don't repay it. You are responsible for the evaluator's fee and any project cost above the $10,000 cap.
If you're trying to figure out what a specific Grand Bay listing's insurance situation actually looks like, or whether an older home on your list is a strong retrofit candidate, Jessica Nguyen can walk through the comparison with you before you write an offer. Schedule a free consultation and bring both listings.
This article is general information, not legal, tax or financial advice. Consult a qualified professional about your situation.