Bayou La Batre's price tags are genuinely low by Mobile County standards.
Flood insurance is a separate cost, and its price depends in part on where a parcel sits on a flood map.
The Number You Saw Online
Depending on which portal you checked and whether you were looking at list price or closed sales, Bayou La Batre's headline number has landed anywhere from about $111,000 to $143,000 over the past year. Listings tracked in April 2026 put the median list price at $125,000. Earlier closed sales data showed a median around $143,000, down double digits from the year before. Either way, the town reads as one of the most affordable addresses on the Alabama coast, and on pure purchase price, it is.
Purchase price and carrying cost are different considerations, and in a shrimping town built along tidal water, the gap between them can be substantial.
Why Insurance Isn't Optional Here
Mobile County's own flood zone maps for the southern part of the county show Bayou La Batre threaded through by Zone AE, the designation FEMA uses for areas with a mapped one percent annual chance of flooding, along with stretches of floodway and Zone VE closer to open water. The Alabama Department of Economic and Community Affairs says a federally backed mortgage on a home in Zone AE requires flood insurance as a condition of the loan. There is no opting out once you're financing.
That single fact does more to shape a Bayou La Batre buyer's monthly payment than the list price does. It also means the insurance conversation needs to happen before an offer goes in, not after the inspection.
What Two Bills Actually Add Up To
Homeowners insurance in Bayou La Batre is already expensive on its own. A statewide analysis of homeowners insurance rates, built from non-binding quotes pulled in February 2026, found that Bayou La Batre and neighboring Belle Fontaine carry some of Alabama's highest premiums, running more than $9,000 a year, trailing only Dauphin Island. That number sits well above the state's already elevated average, which itself has climbed sharply since 2021 as insurers price in storm exposure and construction costs.
Flood coverage is a separate policy entirely, priced by FEMA or a private carrier rather than a home insurer, and it stacks on top. A local flood insurance broker's own book of business for the Bayou La Batre and Chickasaw area shows an average annual flood premium of $2,317, based on 323 active policies as of this spring. For comparison, that same broker's data put the average flood rate in Mobile at $1,020 and in Dauphin at $829, meaning a Bayou La Batre parcel is pricing flood risk at roughly double what nearby markets carry.
Put those two bills next to a mortgage payment and the picture changes. Using the April 2026 median list price of $125,000, a buyer putting 10 percent down on a 30-year loan at 7 percent would land close to $750 a month in principal and interest. Layer in the insurance figures above and the monthly math looks like this:
| Monthly line item | Estimated cost |
|---|---|
| Principal and interest (10% down, 7%, 30-yr) | ~$750 |
| Homeowners insurance (at $9,000/yr) | ~$750 |
| Flood insurance (at $2,317/yr) | ~$193 |
| Total monthly carrying cost | ~$1,693 |
This is illustrative math built from the figures above, not a quote, and actual premiums depend on the specific structure, its elevation, and the carrier. But the shape of it holds. On a house priced to look like the cheapest option on the coast, insurance alone can equal or exceed the mortgage payment itself. A buyer comparing Bayou La Batre to a pricier inland neighborhood on sticker price alone is comparing the wrong number.
Why the Same Town Prices Insurance Differently, Parcel to Parcel
Not every address in Bayou La Batre carries identical risk. The county's flood maps show Zone AE running through most of the developed area, but pockets closer to open water fall into Zone VE, where wave action adds another layer of risk and, usually, cost. Elevation relative to the base flood elevation on a given parcel is the detail that moves a premium up or down, which is why two houses a few streets apart can carry different quotes even at similar list prices.
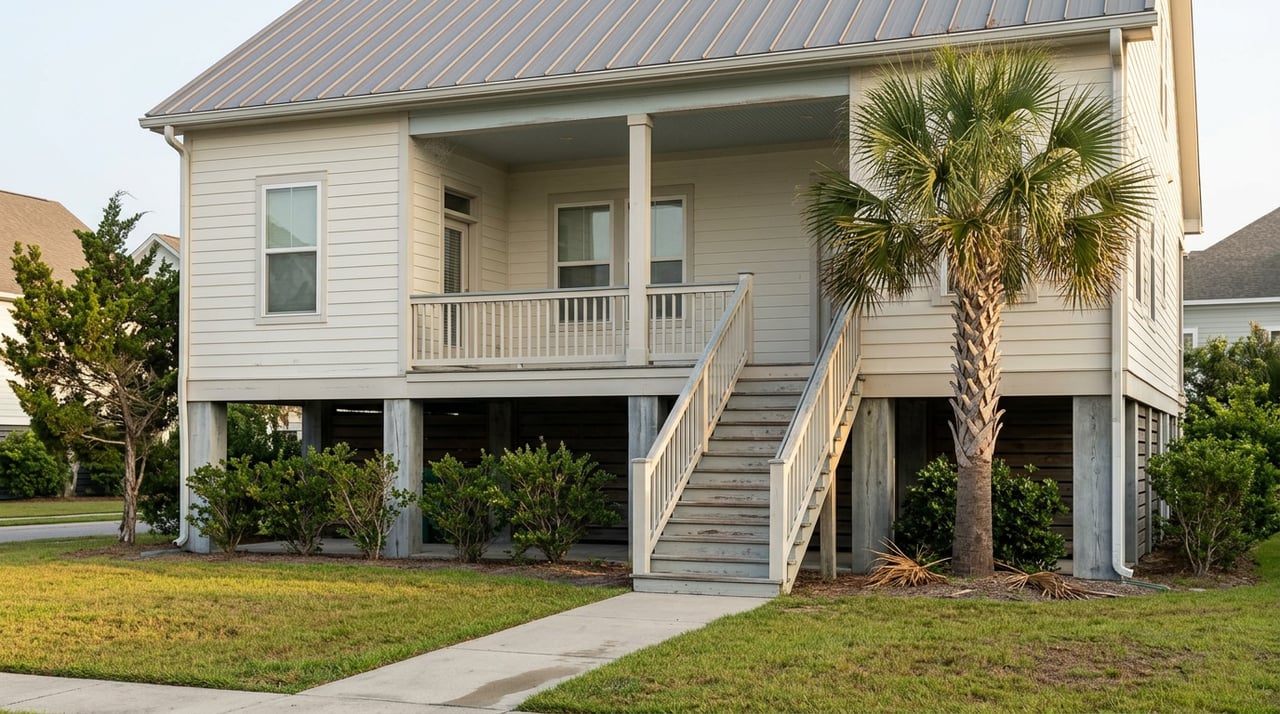
An elevation certificate, prepared by a licensed surveyor, documents how high a structure sits relative to that base flood elevation. A home built up on pilings above the line prices very differently than a slab home sitting at or below it. Before writing an offer, it's worth asking whether the seller already has one on file. If not, getting one during due diligence is a small cost that can prevent a much larger surprise on the insurance quote.
A few questions worth asking before earnest money moves:
- Does the seller have a current elevation certificate, and what does it show relative to base flood elevation?
- Is the home in Zone AE, VE, or one of the smaller lower-risk pockets, and has that changed on any recent map update?
- What has the seller actually been paying for both policies, not just what a quote estimates?
- Is the current flood policy grandfathered under an older rate, and does it transfer to a new owner or reset at sale?
Before You Write the Offer
None of this means Bayou La Batre is a bad place to buy. It means the number that matters is the one at the bottom of the insurance quote, not the one at the top of the listing. Buyers who ask for the seller's actual declarations pages, price out a flood quote early, and factor elevation into the offer are working with real numbers instead of a headline. Buyers who anchor purely to the low list price find out the difference at the closing table, which is a much worse place to learn it.
Flood-zone and insurance history: Check the flood map and ask the seller for the policy information directly.
Frequently Asked Questions
Can I get private flood insurance instead of an NFIP policy in Bayou La Batre? Private flood carriers do operate in coastal Alabama, and for some well elevated properties they can undercut NFIP pricing. Whether that applies to a specific house depends on its elevation certificate and construction, which is why it's worth quoting both before assuming either one is cheaper.
Does a lower purchase price mean a lower total monthly payment in this market? Not automatically. As the math above shows, insurance costs in Bayou La Batre run high enough that a lower sale price doesn't guarantee a lower monthly carrying cost once both policies are factored in. The only way to know is to price out insurance on the specific parcel before making an offer.
If you're weighing a purchase in Bayou La Batre against another Mobile County community, the conversation should start with an actual insurance quote on the specific address, not the number on the listing. Jessica Jenkins-Nguyen can walk through what a given parcel's flood zone and elevation history mean for your monthly numbers before you write an offer. Schedule a free consultation to get the full picture before you fall in love with the price tag.
This article is general information, not legal, tax or financial advice. Consult a qualified professional about your situation.